
Miami-Dade · Car & Home
Car & Homeowners Insurance in Miami, FL: Compare Quotes
Car insurance in Miami is priced by your ZIP code, and home insurance by your roof and the hurricane zone you live in. We compare multiple A-rated carriers on both and explain every offer.
How do I get car insurance in Miami that fits my budget?
Car insurance in Miami costs what each carrier says your ZIP code, your car and your record are worth, so the same driver can see very different offers. Florida asks every registered car for $10,000 of personal injury protection and $10,000 of property damage liability, and most Miami drivers carry more. Comparing several carriers on identical limits shows you what a fair price looks like for your car. We do that comparison across multiple A-rated carriers, free.
Florida Car Insurance Laws for Miami Drivers
Florida's no-fault rules decide who pays first after a crash on I-95, the Palmetto or a Brickell side street. These four set the base of every Miami auto policy.
| Florida law | What it means for a Miami driver |
|---|---|
| Personal injury protection pays up to $10,000 in medical and disability benefits and $5,000 in death benefits (§ 627.736(1), Florida Statutes) | Your own policy pays first for your injuries, no matter who caused the crash. |
| PIP medical benefits require initial care within 14 days of the crash (§ 627.736(1)(a), Florida Statutes) | See a doctor within two weeks of any crash, even one that felt minor, or you can lose those benefits. |
| Without an emergency medical condition, PIP reimbursement is limited to $2,500 (§ 627.736(1)(a), Florida Statutes) | The full $10,000 depends on what the treating provider finds, not on what the policy says on the first page. |
| Every registered vehicle needs $10,000 of property damage liability (§ 324.022(1), Florida Statutes) | Repairs to a newer car can pass $10,000, and the amount above your limit is yours to pay. |
These are legal minimums, not a recommendation. A lender with a loan or lease on your car will also ask for collision and comprehensive.
Homeowners Insurance in Miami: Wind vs. Flood
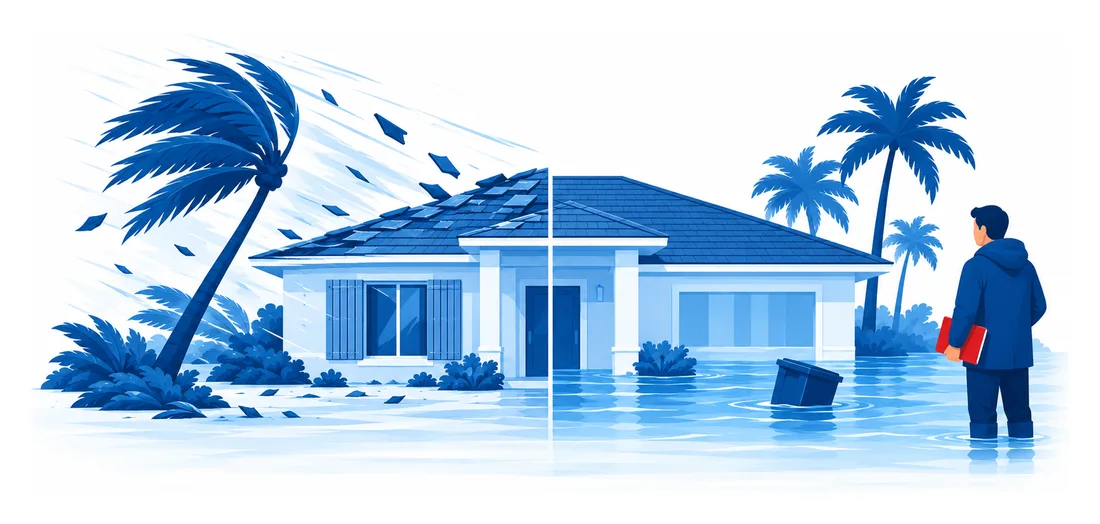
Miami-Dade sits inside the Florida Building Code's High-Velocity Hurricane Zone. A hurricane can damage your home two ways, and a standard policy only answers one of them.
Wind and hurricane damage
Your homeowners policy covers wind, with a separate hurricane deductible. Before issuing it, the carrier must offer you deductibles of $500, 2 percent, 5 percent and 10 percent of the dwelling limit (§ 627.701(3)(a), Florida Statutes). The percentage you pick sets what you pay yourself after a named storm.
Flood and storm surge
Rising water is excluded from a standard homeowners policy, even when a hurricane brought it. It takes a separate policy, and our flood insurance page explains the options. Lenders require one when the house sits in a high-risk flood zone.
What You Need for Car and Home Insurance Quotes in Miami
- The driver's license of every driver in your household, and each car's VIN.
- Your current declarations page, so we can quote the same limits side by side.
- For your home: the year it was built, the roof's age and material, and the square footage.
- Your wind mitigation inspection report, if you have one.
- Any claims in the last five years, on the car or the house.
What happens after I send a Miami quote request to your agents?
A licensed agent at our Kendall office reviews it and gathers the details carriers will ask for. Your Miami address then goes to every carrier that writes it, car and home both, and American US Insurance checks a bundle against two separate policies. You see each offer in plain words, deductible by deductible. Your policy starts only when you say yes.
More Insurance for Miami Drivers and Homeowners
We insure cars and homes anywhere in Florida. Other cities near Miami where we can help with your insurance: Kendall · Hialeah · Doral · Homestead · Fort Lauderdale
Car Insurance Guides for Miami Drivers
Florida Motorcycle Insurance Laws: What Riders Must Know
Is motorcycle insurance required in Florida? Learn what the law asks of riders, the $10,000 medical rule for riding without a helmet, and what to carry.
Read More →
Full-Time RV Insurance in Florida: Living on the Road
Full-time RV insurance in Florida: the liability, personal belongings and domicile rules full-timers need to settle before they live on the road.
Read More →
Boat Insurance Cost in Florida: Key Factors Explained
How much is boat insurance in Florida? Your premium depends on hull value, where you keep the boat, your hurricane plan and the safety credits you earn.
Read More →Get Your Miami Car and Home Insurance Quotes
Tell us about your vehicle, your home, or both. A licensed Florida agent will compare multiple A-rated carriers and explain each offer line by line.
- No obligation, no pressure
- Renewal and claims help after you buy
- A licensed agent compares carriers
Request My Miami Car or Home Quote
Common Questions