
Roofing Contractors · Florida
Florida Roofing Contractor & Roofer Liability Insurance
Florida roofers face difficult underwriting markets after every hurricane season. We keep your license, crew, and active jobs protected across multiple A-rated carriers.
What kind of insurance should a roofing contractor have in Florida?
Roofing insurance in Florida starts with general liability at or above the license floor, which for a roofing contractor is $100,000 of public liability and $25,000 of property damage (Rule 61G4-15.003, F.A.C.). Roofing is construction work, so workers comp applies from the first employee (§ 440.02(20)(b), Florida Statutes). Most roofers also carry commercial auto, a floater for tools and equipment, and an umbrella that meets their contracts. We compare roofing contractor insurance across multiple A-rated carriers.
Roofing Contractor Insurance Risks, Stage by Stage
Every roof moves through the same four stages, and the exposure moves with the crew.
Estimate and permit
Proof of workers comp or an exemption comes before the permit (§ 440.103).
Tear-off and dry-in
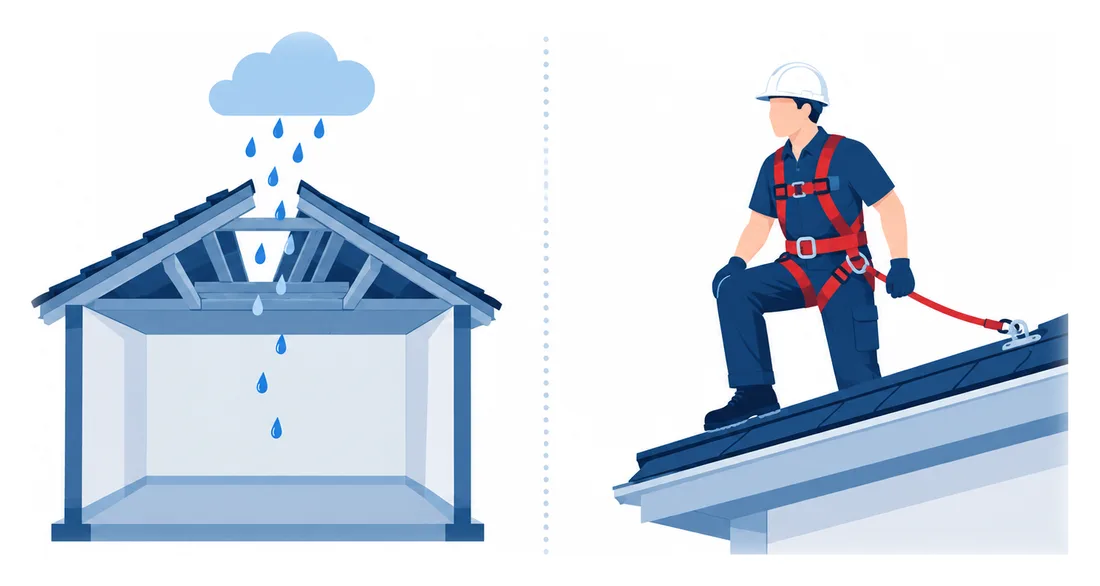
The roof is open, and one afternoon storm can soak the rooms below.
Installation
Crews work at height with torches, kettles and nail guns.
Final inspection and warranty
A leak that shows up later falls under completed operations coverage.
Roofing General Liability vs. Workers Comp
Roofers need both, because they answer to different people: the property owner and the crew.
General liability
Pays the homeowner or building owner when your work causes damage or injury, such as rain through an open roof or a bundle dropped on a car. It also pays for your defense if they sue. The license and most contracts ask for it.
Workers comp
Pays your own roofers' medical care and part of their wages after a fall, a burn or heat illness. In Florida roofing it starts with the first employee. Our workers comp insurance page explains class codes and audits.
Florida Roofing Contractor Insurance Requirements
Insurance, permits and storm-season sales all have rules. These are the ones that touch your coverage and your contracts.
| What Florida law says | What it means for your business |
|---|---|
| Public liability of $100,000 and property damage of $25,000 for a roofing contractor's license (Rule 61G4-15.003, F.A.C.) | The license floor. Re-roof contracts and commercial jobs often ask for $1,000,000 per occurrence. |
| Workers comp from the first employee in construction, roofing included (§ 440.02(20)(b), Florida Statutes) | Roofing payroll has its own class code and rate, so accurate payroll records keep the year-end audit fair. |
| Proof of workers comp or an exemption before a permit issues (§ 440.103, Florida Statutes) | A missing certificate stops the permit, and the job with it. |
| No rebates, gifts, deductible waivers or other incentives to a homeowner for a roof inspection or claim, and no advice on policy coverage without a public adjuster license (§ 489.147, Florida Statutes) | A sales rule, not an insurance rule, with fines of up to $10,000 per violation. It shapes how you market roof work after a storm. |
These rules touch your insurance and your sales. They are not legal advice or a quote.
Before You Call for a Roofing Insurance Quote
- Your license number and class, roofing or general, and the counties you work in.
- Your split between residential re-roofs, new construction and commercial roofs.
- Payroll by job, the number of roofers on staff and any subcontractors you hire.
- The methods you use, such as torch-down, hot tar, tile or metal.
- Five years of claims and the declarations page of your current policy.
Which roofing insurance companies write Miami roofers?
Several A-rated carriers still write roofers here, but many limit height, torch work or storm-damage jobs, and their appetite shifts after each hurricane season. American US Insurance follows that market from Kendall, so a roofer who hears no from one carrier can still see offers from others. Each roofing liability insurance answer, yes or no, comes with its reason, read against your payroll, methods and claims history. Roofers from Homestead to Fort Lauderdale keep their permits and contracts moving.
Additional Business Insurance Options
Roofing Insurance Guides

Business Owners Policy vs. General Liability: Which Fits?
Business owners policy vs. general liability: a BOP adds property and business income coverage to liability. How to tell which your Florida business needs.
Read More →
Payment Bond vs. Performance Bond: How Each One Works
Payment bond vs. performance bond: one guarantees the job gets finished, the other that subs and suppliers get paid. When Florida public jobs need both.
Read More →Get a Roofing Contractor Insurance Quote
Tell us your crew size, roofing methods, and operating counties. We compare multiple A-rated Florida carriers and explain every limit and exclusion before you bind.
- No obligation, no pressure
- Renewal and claims help after you buy
- A licensed agent compares carriers
Request My Roofing Insurance Quote
Common Questions