
Manufacturers & Plants · Florida
Florida Manufacturing Insurance & Product Liability
A jammed press or a failed part can halt operations. Florida manufacturing insurance covers your plant, machinery, and products. We compare multiple A-rated carriers to protect your business.
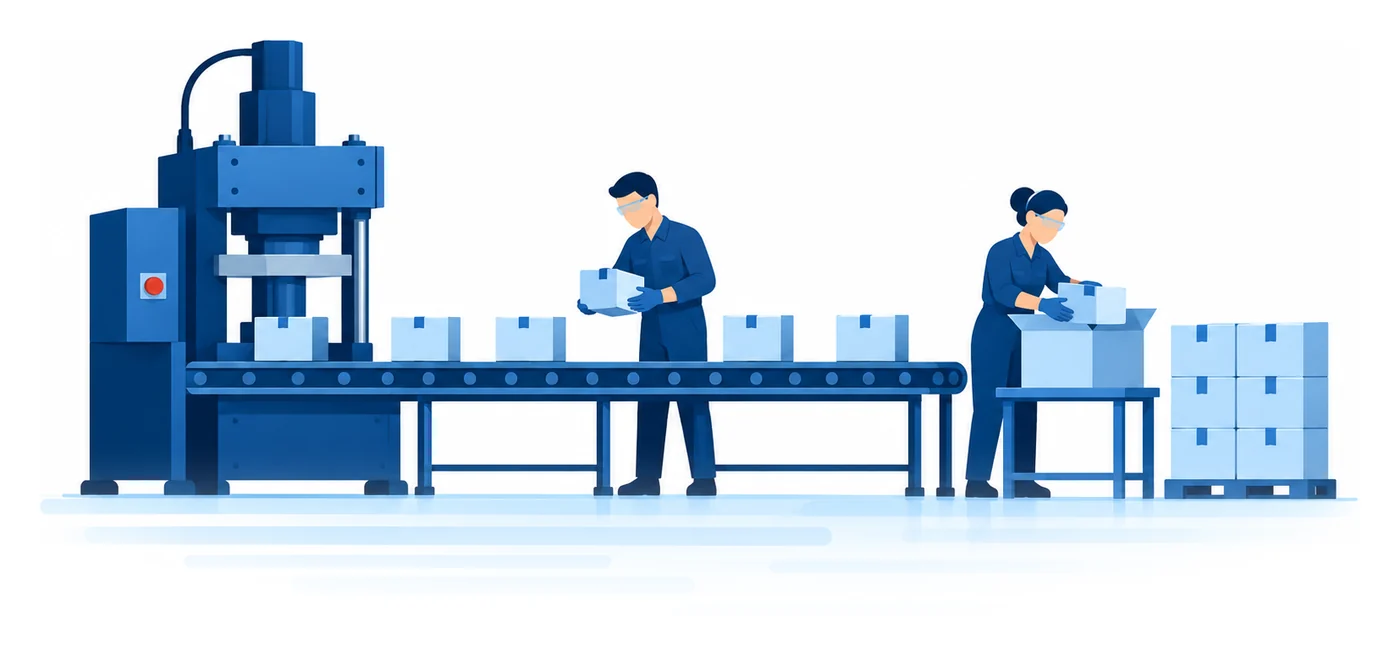
What does manufacturing and product liability insurance cover in Florida?
Manufacturing insurance is a comprehensive commercial package. It covers the factory building and equipment breakdown, provides workers compensation for your floor staff, and most importantly, includes product liability coverage if a defective item you produce harms a consumer after it leaves your facility.
Manufacturing Liability Insurance: Plant vs. Product
A manufacturer faces two kinds of liability claims, and they arrive at very different times.
At the plant: premises liability
Pays when a visitor, a driver or a vendor is hurt at your plant, or when your operations damage someone else's property. It is the part of general liability insurance most businesses already know.
After the sale: product liability
Pays when a product you made injures someone or damages property after it leaves your dock, and pays for your defense. A part sold to another manufacturer can still bring a claim years later.
Commercial Insurance for Manufacturers in Four Parts
These four policies carry most of the weight for a Florida plant. Many carriers write the first three as one package.
Product liability
Answers injury and damage claims tied to what you make, including a component inside someone else's product, and pays for your legal defense.
Machinery and stock
Commercial property covers the building, presses, conveyors, raw materials and finished goods against fire, wind and theft. Equipment breakdown covers a machine that fails on its own.
Workers comp
Pays an operator's medical care and part of lost wages after a caught hand, a lifting strain or a burn on the line.
Cyber liability
Pays to restore systems and answer claims when ransomware stops your production line or exposes customer data.
Florida Laws Behind Manufacturing Insurance
Florida limits how long a product claim can wait and decides when your workers must be covered. These rules shape the policy you buy.
| Rule | What it means for your plant |
|---|---|
| No product liability suit may be brought for harm caused by a product with an expected useful life of 10 years or less if the harm came more than 12 years after delivery to its first purchaser or lessee (§ 95.031(2)(b), Florida Statutes) | Product claims can still arrive long after the sale, so keep records of what you shipped, to whom and when. |
| Commercial aircraft, vessels of more than 100 gross tons, commercial railroad equipment and improvements to real property fall outside that 12-year repose (§ 95.031(2)(b)1., Florida Statutes) | Parts for planes, ships, trains or buildings can carry claims for longer, and carriers ask about them. |
| A manufacturing business with four or more employees must carry workers comp (§ 440.02(20)(b)2., Florida Statutes) | Machine operators, assemblers, drivers and office staff all count toward the four. |
| Your distributor and retailer contracts | Buyers often ask to be added to your products coverage with a vendors endorsement, and they set the limit they expect. |
The statutes above shape when claims can come. They are background for your coverage, not legal advice or a quote.
Prepare These for a Manufacturing Insurance Quote
- What you make, who buys it and the states and countries it ships to.
- Your yearly sales and your payroll, split by plant and office.
- Your machinery list with values, and your building's age, roof and sprinklers.
- Your supplier and distributor contracts, with the insurance terms they set.
- Your claims and product recalls from the last five years.
How do South Florida manufacturers compare carriers on product claims?
Plants in Medley, Hialeah, Doral and Kendall send one file to American US Insurance and let us shop it. Insurance for manufacturing companies turns on what you make and who buys it, since parts sold to other plants and goods sold to the public bring different claims. The offers come back side by side, with each one's product liability limit, vendors endorsement and recall terms spelled out. Owners decide knowing how each carrier treats a claim that arrives years after the sale.
Additional Business Insurance Options
Manufacturing Insurance Guides

Business Owners Policy vs. General Liability: Which Fits?
Business owners policy vs. general liability: a BOP adds property and business income coverage to liability. How to tell which your Florida business needs.
Read More →
Payment Bond vs. Performance Bond: How Each One Works
Payment bond vs. performance bond: one guarantees the job gets finished, the other that subs and suppliers get paid. When Florida public jobs need both.
Read More →Request a Manufacturing Insurance Quote Online
Tell us what you manufacture, where it ships, and your contract limits. A licensed agent will compare multiple A-rated carriers and explain your product liability terms clearly.
- No obligation, no pressure
- Renewal and claims help after you buy
- A licensed agent compares carriers
Request My Manufacturing Insurance Quote
Common Questions